

Social Security Advisor
Make the Most of Your Benefits
Social Security is one of the biggest financial decisions you’ll ever make. The timing and strategy behind how you claim can mean tens of thousands of dollars or more over your lifetime. Keenly’s Social Security advisor, Casey Conley, RSSA®, helps you understand every option before you file, so you get it right the first time.
What does a Social Security advisor do?
A Social Security advisor specializes in one thing: figuring out when and how you should claim. That includes your own benefit, spousal and survivor benefits, and how your choice interacts with taxes and Medicare. Social Security Administration staff can explain the rules, but they are prohibited from advising you on the best claiming strategy for your situation
What is a Registered Social Security Analyst?
A Registered Social Security Analyst® (RSSA®) is a credentialed professional trained specifically in the rules, strategies, and nuances of Social Security. Unlike a general financial advisor, an RSSA has completed a rigorous eLearning program through the National Association of Registered Social Security Analysts (NARSSA), passed a proctored national exam, and is required to maintain ongoing education in Social Security law and planning.
That means you get a dedicated expert who has studied the system in depth and knows how to find opportunities most people miss entirely.
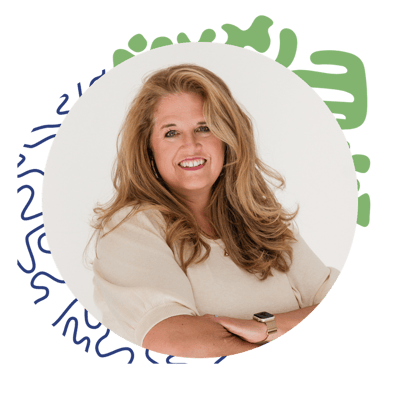
Meet Casey Conley, RSSA®
Casey Conley is a Registered Social Security Analyst® and part of the Keenly team. She earned her RSSA designation so she could be a more complete resource for her clients and help with the full picture of their financial wellbeing.
Driven by helping people save money and plan for their future, she has a gift for connecting with people and breaking down complex topics into something that makes sense. Whether you're five years out from retirement or closer than you'd like to admit, she'll help you understand your options and walk away with a clear plan.
Why does Social Security claiming strategy matter so much?
People can assume that claiming Social Security is straightforward. You turn 62 (or 65, or 67) and you sign up. But the timing and strategy behind how you claim can have a dramatic impact on how much you receive, both month to month and over your lifetime.
Claiming at 62 (the earliest option) can permanently reduce your monthly benefit by up to 30% compared to waiting until your full retirement age.
Delaying until 70 can increase your monthly benefit by 24–32% beyond your full retirement age amount, a difference that compounds every single month for the rest of your life.
For married couples, coordinating when each spouse claims can mean tens of thousands (sometimes hundreds of thousands) of additional dollars in lifetime benefits. The lifetime benefit for a couple can easily reach $1–$2 million.
96% of Americans don't optimize their Social Security, and the average household leaves $111,000 on the table as a result.
The Social Security Administration has over 2,700 rules governing benefits, and SSA representatives are prohibited from giving you personal claiming advice. There are few other reliable resources. That's why you should meet with an RSSA.
Social Security is likely one of the largest assets you'll ever have, and the claiming decision is largely permanent. There are no do-overs. The right answer looks different for everyone; your health, work history, spouse's situation, other retirement income, and goals all factor in.
Social Security is more than a retirement check
Many people think of Social Security as something you collect when you retire. Actually, it’s a guaranteed, lifetime benefit with annual cost-of-living adjustments (COLA), and it covers far more situations than most people realize.
Social Security provides benefits for people who are:
- Married: spousal benefits of up to 50% of your partner's benefit
- Divorced: you may qualify based on an ex-spouse's record after 10+ years of marriage
- Widowed: survivor benefits can be a critical source of ongoing income
- Single: maximizing your own benefit with the right claiming age is essential
- Self-Employed: strategic options exist to reduce payroll taxes while protecting your benefit
- Disabled: SSDI and disability-related benefits are often misunderstood and underutilized
- Parents of dependent or disabled children: children may qualify for benefits based on a parent's record
For most Americans, Social Security is the foundation of retirement income. Getting the strategy right matters.

What the analysis includes
Here's what an analysis looks like in practice: Schedule a meeting with Casey →
Personalized benefit analysis
Casey reviews your Social Security earnings record to project your benefit amounts at various claiming ages.
Break-even analysis
You'll see how long it takes different claiming strategies to "break even" and which approach maximizes your lifetime payout based on your specific situation.
Spousal and survivor benefit planning
For couples, Casey reviews both records and models to develop a coordinated strategy that maximizes combined lifetime income.
Medicare coordination
Casey will make sure your Social Security claiming strategy aligns with your Medicare enrollment to avoid costly surprises.
Claiming guidance
When you're ready to file, Casey can walk you through exactly how and where to do it so the process is smooth and stress-free.
Scenario breakdown
You'll receive a comprehensive, easy-to-follow report showing exactly what you'd receive under different filing scenarios. The full process typically takes one to two weeks.
A real example: how one couple’s claiming strategy changes everything
Here's a simplified example of a claiming strategy.
Paul and Alice, both age 62, with a Full Retirement Age of 67:
- Paul's projected benefit (PIA): $3,000/month
- Alice's projected benefit (PIA): $1,000/month
|
Strategy |
Paul |
Alice |
Combined Monthly |
|
Both claim at 62 |
$2,100 |
$975 |
$3,075 |
|
Both claim at Full Retirement Age (67) |
$3,000 |
$1,500 |
$4,500 |
|
Maximized strategy (Paul at 70, Alice at FRA) |
$3,720 |
$1,500 |
$5,220 |
That's a difference of more than $2,100 per month, or over $25,000 per year, between the least- and most-optimized strategies. Over a 20-year retirement, that adds up fast.
Every situation is different, but this is the kind of analysis Casey runs for her clients.
How to choose a Social Security advisor
Every financial professional specializes in Social Security. When you compare advisors, look for:
A Social Security-specific credential - The RSSA® and the National Social Security Advisor (NSSA) designation are two examples. A CFP® is broader, covering retirement planning generally.
A clear deliverable - You should receive a written analysis of your claiming options, not just a conversation.
Transparent fees - Ask what’s included and how you’re charged before you commit.
Experience with your situation - single, married, divorced, widowed, self-employed, or collecting disability.
Frequently Asked Questions
1. Do I need a Social Security advisor?
You don’t need one to file, but the claiming decision is largely permanent and the rules are complex, with more than 2,700 provisions in SSA’s program guidance. An advisor is most valuable if you’re married, divorced, widowed, self-employed, or have other retirement income that affects taxes and Medicare premiums.
2. What does a Social Security advisor do?
A Social Security advisor reviews your earnings record, projects your benefit at different claiming ages, models spousal and survivor strategies, and shows you the lifetime impact of each option. Casey also coordinates your claiming decision with your Medicare enrollment and walks you through how and where to file.
3. What’s the difference between a Social Security advisor and a financial advisor?
A general financial advisor typically focuses on investments and overall planning. A Social Security advisor concentrates on claiming rules and strategy. An RSSA® has completed specialized training in Social Security and passed a proctored national exam. Many people use both.
4. Can’t I just ask the Social Security Administration when to claim?
SSA representatives can explain how the program works and help you file, but they are prohibited from giving personalized advice on the best claiming strategy. That gap is what a Social Security advisor fills.
5. When should I meet with a Social Security advisor?
Ideally several years before you plan to retire, but it’s never too late. Even if you’re close to filing age or have already started collecting, there may still be options worth exploring.
Ready to get started?
Social Security planning is too important to leave to chance. Schedule a free consultation with Casey today about your situation and how to make the most of what you've earned.
The information provided on this page is for general informational purposes only and does not constitute financial or legal advice. NARSSA has no affiliation with the Social Security Administration or any other government agency. Please consult with a qualified advisor for guidance specific to your personal situation.